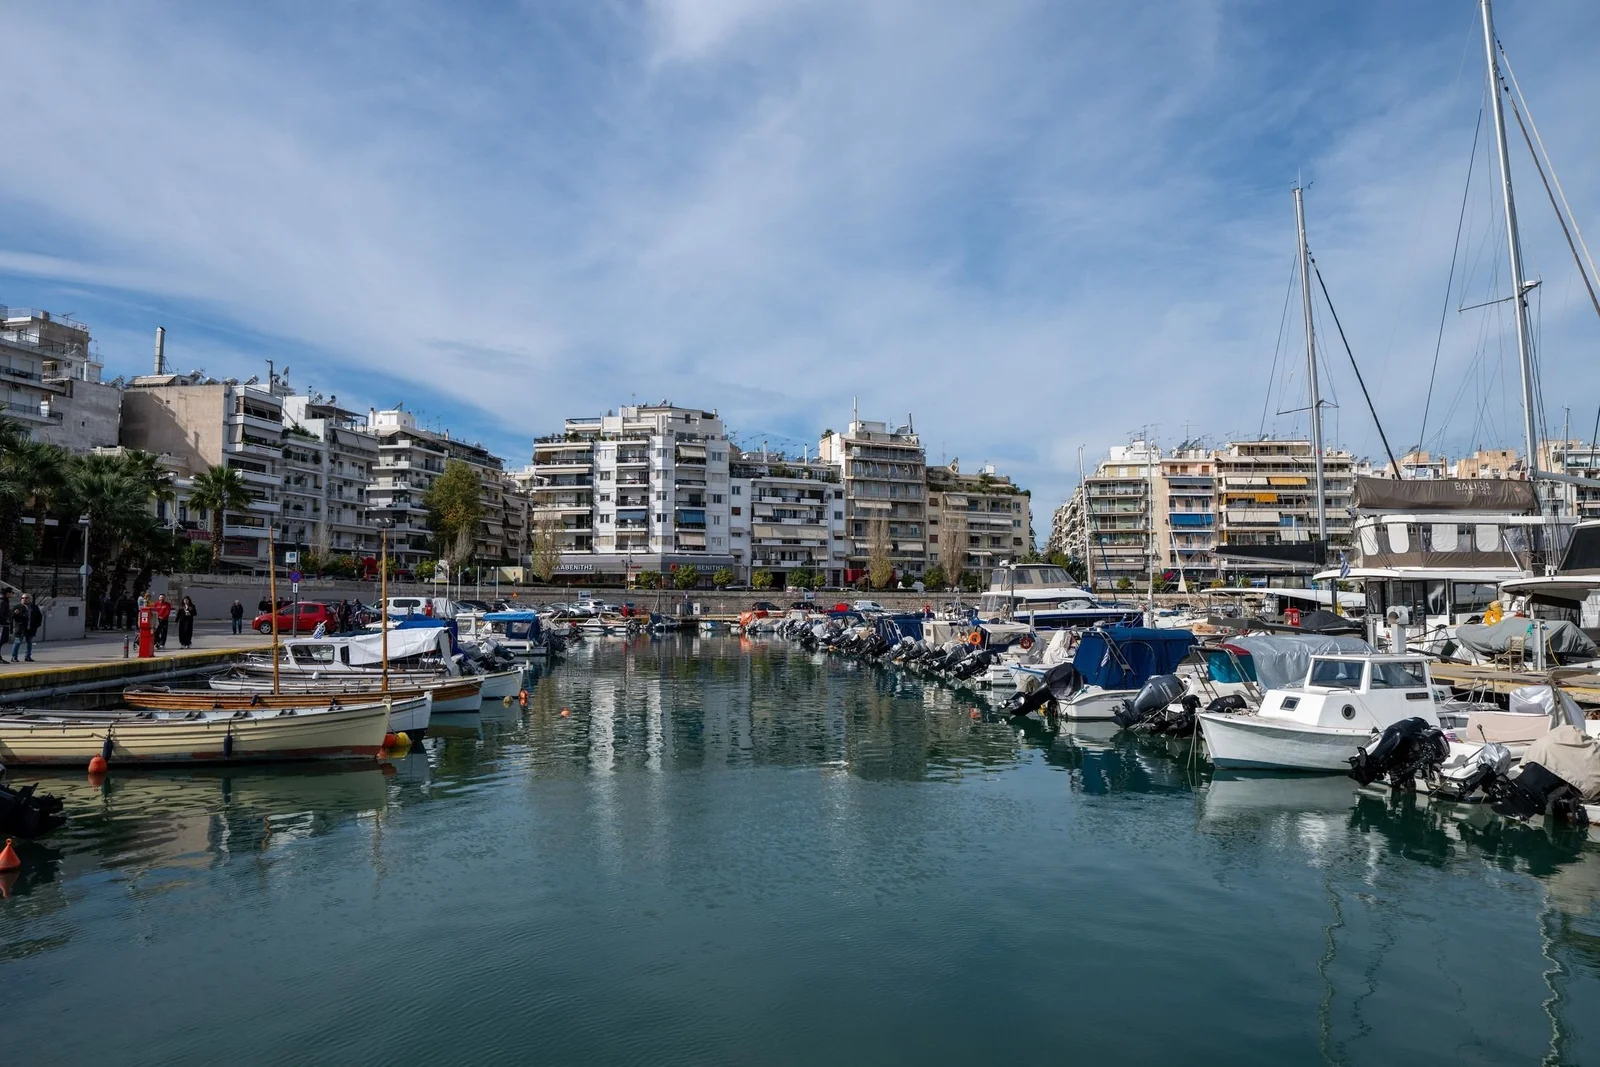
Quick answer: Piraeus is Attica’s port-city investment corridor, Greece’s largest commercial harbour, a cruise hub, and a gentrifying residential municipality west of central Athens. Suburban asking prices often start around €2,400 per square metre; Kastella and Mikrolimano run higher. The entire municipality sits in the €800,000 Golden Visa zone with the 120m² single-property rule. Gross long-term yields are measured at about 4.9%, below the Athens city-wide 5.43% and below working-class northern districts at 6.0 to 7.5%. Regeneration signals such as Piraeus Gate (1,000+ planned homes) support a long hold thesis, but port logistics, building vintage, and title quality still determine whether a specific unit works.
Quick answer: Piraeus is Attica, so a Golden Visa file needs €800,000 on one deed with 120 square metres of certified main usable area. What distinguishes it from every other Attica address is that the port is a participant in the property market rather than a backdrop to it: freight routing, terminal operations and berth traffic set which streets are lettable and which carry a permanent discount, and they do it at a granularity of a few hundred metres.
It is also a city in its own right, its own municipality, its own commercial centre, its own working population, connected to Athens by Metro Line 1 and the tram. That makes it a competitor for tenants rather than a dormitory.
The harbour is an employer and a boundary at the same time
Piraeus is the largest passenger port in Europe and a major container gateway, and both halves of that matter to a residential buyer in opposite directions.
As an employer it produces exactly the tenant a Golden Visa asset needs. Shipping companies, freight forwarding, marine services, customs, the ferry operators and the businesses attached to them staff the city year-round, and a twelve-month residential lease, the only letting a qualifying deed may carry, has a straightforward counterparty here.
As an operation it draws hard lines through the map. Container terminals run continuously. Freight concentrates on specific roads and does not move. Cruise and ferry berths generate seasonal pedestrian surges on particular streets. A flat that faces one of these is discounted permanently, and a flat two blocks inland is not.
Three checks belong on foot rather than on a map, and all three are cheap:
- What the windows face at seven on a weekday morning, because port operations are scheduled, not ambient.
- Which road the trucks use, since freight routing is stable and visible.
- The walk to the Metro or tram, which is what a professional tenant is buying and what protects the rent when a shipping cycle turns.
Kastella, the centre and the grid are three different markets
Piraeus is not one price. The hillside above the harbour, the commercial centre and the flat working grid behave differently enough that comparing them on a single €/m² figure misleads.
| Sub-market | What it is | What it means for a long let |
|---|---|---|
| Kastella and the hill | Sea aspect, quieter, lifestyle stock | Premium paid per square metre of view, which the 120 m² certificate does not count |
| Central Piraeus | The commercial and administrative core | Deepest year-round demand, closest to transport |
| The port grid | Flat working district near the terminals | Lowest entry, most exposed to freight and operations |
| Marina and Zea | Yacht basin frontage, restaurants | Priced on amenity, thinner tenant pool |
For a Golden Visa buyer the useful question is not which is best but which the €800,000 lands in. On the hill the view premium pushes the price per certified square metre up, so the size test tightens. In the grid the threshold sits well above ordinary local transaction levels, so the buyer is entering a thin boutique layer rather than the local market. The ΕΛΑ Suites Kastella and Evripidou reviews cover one scheme on each side of that line.
A city, not a commute
Piraeus has a municipal government, a university, a court complex, hospitals and a commercial centre that serves its own population rather than overflow from Athens. Metro Line 1 runs to Monastiraki and Omonia; the tram runs along the coast; the suburban rail connects to the airport corridor.
The practical consequence for an owner is that vacancy here is not driven by Athens. A tenant working in Piraeus does not have an Athens alternative that is equally convenient, which is a materially different position from a suburb where every tenant is choosing between locations. It also means Piraeus rents move on shipping and local employment, and those are not the same cycle as central Athens offices.
What the €800,000 threshold does in a city that transacts below it
Ordinary Piraeus residential stock sits far below the Golden Visa floor. That is not a problem to be solved but a structure to be understood: the qualifying purchase is not a bigger version of the local transaction, it is a different product bought by a different buyer.
Two consequences follow. Comparables are thin, because there are few genuine €800,000 residential transactions in the municipality outside new boutique schemes, so a valuation here rests on the scheme rather than on the street. And the rent does not scale with the price, a unit that cost four times the local average does not let for four times the local rent, so the yield compresses. Neither is a reason to avoid Piraeus; both are reasons to buy it for the permit and the tenant rather than for the income multiple.
Older stock and what an engineer can certify
Much of the city’s residential fabric is mid-century apartment building, and the usual Greek questions apply with force: enclosed verandas, converted basements, rooftop additions, and internal changes that never reached a permit. On a Golden Visa file those are not negotiating points but eligibility items, because an un-legalised alteration does not count toward main usable area.
Ask for the Electronic Building Identity and an engineer’s certificate stating enclosed area before the preliminary agreement. On port-city stock the gap between the marketed figure and the certified one is frequently wide, and the due diligence guide covers the rest of the file.
Millions of passengers, almost none of whom stay
Piraeus handles enormous passenger volumes across its cruise berths and its ferry gates, and that figure gets quoted at buyers as though it were demand. It is not. Both passenger flows are structurally designed not to produce an overnight stay.
A cruise call lands passengers in the morning and reboards them in the evening. They spend the day in Athens, not in Piraeus, and they sleep on the ship. A ferry passenger heading for the islands is in the port for the interval between arriving and departing, which the schedule keeps as short as it can. Both groups walk through the district in large numbers and neither is a tenant, a guest or a customer for anything that takes more than an hour.
The exception is narrow and worth stating precisely, because it is the one case where the volume is real: a passenger whose ferry leaves early or arrives late enough to force a night in the port. That produces genuine demand for accommodation near the gates, it is seasonal, and it is the kind of one-night turnover that short-term letting exists to serve. Which means it is exactly the demand a Golden Visa qualifying asset is forbidden from taking. On a qualifying deed the port’s most distinctive source of accommodation demand is unavailable to you by law, and any projection that includes it is describing a property you are not allowed to run.
What is left is the demand this page has already described: people who live and work in a city of roughly 160,000 residents with its own employment base, its own commercial centre and its own schools. That is a solid, year-round, unglamorous letting market, and it is the one to underwrite. It is also the reason Piraeus behaves more like a mid-sized Greek city than like an Athens suburb, and why the Athens investment guide treats the two separately.
One qualification, because it cuts the other way. The port’s employment base is real even though its passengers are not: the shipping offices, the port authority, the agencies, the ferry operators and the maritime services clustered around them employ people who do sleep here, on salaries that support the middle of the rental market. That is the demand a Piraeus purchase rests on. It is unaffected by cruise traffic, it does not move with the ferry timetable, and it is the reason the district’s occupancy holds up in months when the port is quiet.
The ferry gates and the cruise berths are not even in the same part of the port, which is worth knowing before viewing: a listing described as near the port could mean either, and they are different streets with different traffic at different hours.
Buyers arriving from Athens routinely underestimate how self-contained this is. Piraeus has its own commercial centre, its own municipal identity and a population that in large part works, shops and schools inside the city rather than commuting into Athens for any of it.
The practical test for any Piraeus listing: ask who sleeps here on a Tuesday in February. If the answer depends on a ferry timetable or a cruise schedule, the answer is nobody.
Buyer scenarios in a port city
| Scenario | Where it points | The caveat that matters |
|---|---|---|
| Permit-first, wants a reliable tenant | Central Piraeus, near Metro Line 1 | €800,000 sits well above ordinary local transactions, so comparables are thin |
| Permit plus personal use | Kastella and the hill | The view premium raises the price per certified square metre, tightening the 120 m² test |
| Lowest entry per square metre | The port grid | Check freight routing and what the windows face before anything else |
| Yield-focused | Inner Athens instead | Piraeus rents do not scale with a Golden Visa purchase price |
Risks and red flags specific to this city
Port exposure is the one that does not improve: terminal operations, freight roads and berth traffic are fixed infrastructure, and a discounted street stays discounted. Mid-century apartment stock carries the usual unpermitted alterations, which do not count toward main usable area. And a shipping-cycle downturn affects local employment directly, so a tenant base that looks deep in a good year is more cyclical than an Athens office district.
Next steps: the hill scheme and the grid scheme compared · the other dense Attica market with a year-round tenant.
Frequently Asked Questions
Piraeus suits investors who want Attica exposure at lower entry prices than central Athens or the Riviera, with port-driven employment, cruise traffic, and regeneration catalysts such as Piraeus Gate. Suburban stock often starts around €2,400 per square metre. Gross long-term yields are measured at about 4.9%, below the Athens average of 5.43% and below working-class northern districts at 6.0 to 7.5%.
Quality stock spans roughly €2,400 per square metre in outer suburbs to €3,800 or more in Kastella and Mikrolimano. At €2,400 per square metre, €800,000 buys approximately 333 square metres, well above the Golden Visa 120m² minimum.
Yes. Piraeus is within Attica's prime zone under Law 5100/2024. The minimum is €800,000 in a single property of at least 120 square metres. Short-term tourist rentals on the qualifying asset are prohibited; long-term leases are permitted.
Gross long-term yields are measured at about 4.9% on mid-market apartments, below working-class northern Athens at 6.0 to 7.5% but above the Riviera at 3.8% to 4.5%. Net yields after tax and costs land roughly 1.0 to 1.5 points below gross.
Piraeus Gate is a regeneration project signalling more than 1,000 new homes near the port corridor. It indicates institutional confidence in Piraeus as a long-term live-work district, but it is not a substitute for unit-level due diligence on title, build quality, and location.
Compare Kastella for gentrified hillside stock, Mikrolimano for yacht-harbour lifestyle units, central metro-linked districts for commuter tenants, and outer suburbs for lowest per-square-metre entry near €2,400. Match submarket to yield target and hold horizon.
Port noise and traffic, uneven older building quality, title and illegal-extension issues, Golden Visa STR restrictions, regeneration overselling on distant units, and thinner resale liquidity in outer suburbs. Run the full due diligence checklist before signing.
Piraeus in one paragraph
Piraeus is Athens’ port city and its most-improved investment story of the past decade: metro line 3 now reaches the port, the cruise and ferry terminals anchor year-round employment, and Kastella and Mikrolimano carry genuine sea-view scarcity. It falls inside the €800,000 Attica prime tier, so the Golden Visa arithmetic is demanding, but long-term gross yields on renovated stock run higher than the southern Riviera because entry prices are lower against comparable rents. The risks are specific rather than general: older building stock with legalisation history, uneven block-by-block quality, and a port-adjacent noise and traffic profile that varies sharply within a few hundred metres.
Read next
Athens Golden Visa €800K: Which Areas Qualify in 2026
Athens €800K Golden Visa zone: Piraeus, Glyfada, Voula, Vouliagmeni, Ellinikon. Prices, 120m² rule and area guide for 2026.
Property for Sale in Athens: Prices by District, 2026
Kolonaki asks about €5,409 per m² and Patisia €1,731, a threefold spread inside one city. Where the Riviera sits, and why Athens yields beat the islands.
Greece Property Investment Guide 2026: Yields & Data
Greece property investment 2026: 41,743 transfers worth €4.2B, +7.5% price growth, Athens yields to 5.43%, Golden Visa tiers and the Ellinikon regen.
Due Diligence Greece Property: The Complete 2026 Checklist
Due diligence Greece property: title search, cadastre, ENFIA arrears, permits, engineer survey, co-ownership, mortgages, Golden Visa tier. Full checklist.
Greece Rental Yields 2026: Real Net Numbers by City
Measured Greek yields by city and unit size, what short lets really earn, and what survives tax, management and vacancy.
Athens Airbnb Moratorium 2026: Zones, Rules and Impact
Athens STR moratorium through end-2026: density caps in Kolonaki, Koukaki and centre. Separate from the Golden Visa rental ban, rules explained.
Get your Greece property shortlist
Share your budget, region (Athens, Crete, islands, or Peloponnese), and Golden Visa goal. We reply within one business day with matched options and next steps.