Quick answer: Both zones sit in the same €800,000 Attica tier, and the comparison most articles draw between them is the wrong one. The centre’s yield reputation rests on Kipseli and the transitional districts at €2,000 to 2,800 per square metre. Spending €800,000 on a single title at those prices means buying around 300 square metres, and that stock is not what Athenian apartment blocks contain. At the qualifying threshold the centre you can actually buy is Kolonaki and its neighbours, where gross yields run 3.5% to 5%, below the Riviera, not above it.
So the real choice at €800,000 is between prime centre and coast, and on the numbers the coast wins on income as well as on lifestyle. The Kipseli yield case belongs to buyers at the €400,000 regional tier or to anyone buying outside the Golden Visa entirely.
Athens investors rarely choose “Athens”, they choose a submarket. The €800,000 threshold applies equally to a Kipseli apartment and a Voula seafront flat, but the return profile, regulatory overlay, and buyer pool differ sharply. This comparison maps Glyfada and Voula against Kipseli and the wider center for investors who have committed to Attica but not to a district.
Hub guides: Athens property investment guide · Athens Golden Visa €800,000 areas · Area pages: Glyfada · Voula · Kallithea
Riviera vs Center at a Glance
| Criterion | Athens Center | Athens Riviera (South) |
|---|---|---|
| Golden Visa tier | €800,000 | €800,000 |
| 120 m² minimum | Yes | Yes |
| STR on GV asset | Prohibited | Prohibited |
| Indicative €/m² | €3,400+ centre avg; Kipseli €2,000 to 2,800; Kolonaki €4,500 to 6,000+ | €3,200+ south avg; Glyfada/Voula €3,500 to 5,500+ |
| Gross LTR yield, city-wide | 5.43% average across all price points | 4 to 5.5% typical |
| Gross LTR yield on €800,000 single-title stock | 3.5 to 5% (Kolonaki grade) | 4 to 5.5% (Glyfada/Voula grade) |
| STR moratorium (new licences) | Yes, central saturated zones | No, standard ΑΜΑ rules (non-GV) |
| Appreciation driver | Urban gentrification, metro | Ellinikon €8B regeneration |
| Primary tenant | Young professionals, students, locals | Families, expats, coastal lifestyle |
| Buyer profile | Yield-focused LTR | Appreciation + lifestyle resale |
Same Golden Visa Tier: Different Economics
- €800,000 minimum in one residential title
- 120 square metres minimum usable area (engineer certificate)
- No short-term tourist rentals on the qualifying asset
Tier parity is where most comparisons stop, and it is where the interesting constraint starts. The threshold has to be met on one title. Divide €800,000 by each district’s price per square metre and the answer tells you what you would have to find.
| Budget arithmetic | Kipseli (~€2,400/m²) | Kolonaki (~€5,200/m²) | Glyfada (~€4,000/m²) |
|---|---|---|---|
| €800,000 on one title buys | ~333 m² | ~154 m² | ~200 m² |
| Typical apartment in that stock | 80 to 120 m² | 100 to 180 m² | 100 to 150 m² |
| Does the arithmetic meet the stock | No: you would need three flats | Yes | Yes |
| GV 120 m² rule | Achievable, but not on one deed at this budget | Achievable | Achievable |
The Kipseli column is the finding. A 333 square metre single residential title in a 1960s Kipseli apartment block is not a rare listing; it is close to a non-existent one, and buying three flats does not help because the threshold and the 120 square metre certificate both attach to a single deed. Merging adjacent units is legally possible and slow, and it is a construction project rather than a purchase.
The practical consequence: a Golden Visa buyer at €800,000 who wants the centre is buying Kolonaki, Mets or Koukaki at prime prices. They are not buying the Kipseli yield. Any comparison that quotes Kipseli’s 6 to 7.5% next to an €800,000 budget is quoting a return the reader cannot execute.
Detail: Greece Golden Visa property tiers 2026 · Greece Golden Visa no short-term rental
Price Map: Glyfada, Voula, Kipseli, and Center
The spread across Athens is roughly fourfold, from about €2,000 per square metre in transitional Kipseli to €5,000 to €8,000-plus in Vouliagmeni. Between those, central Athens averages €3,400-plus, Glyfada runs €3,500 to €5,500-plus and Voula €4,000 to €6,000-plus. Kipseli is the yield anchor of the comparison: rents there are strong relative to prices in a district that has not repriced toward Kolonaki levels. Greek Property Group Q3 2025 reference data frames the spread:
| Submarket | Indicative asking €/m² | Investment character |
|---|---|---|
| Athens Centre (avg) | €3,400+ | Deep tenants; moratorium zones |
| Kipseli / transitional | €2,000 to 2,800 | Yield standout 6 to 7.5% LTR |
| Kolonaki / prime centre | €4,500 to 6,000+ | Prestige; moratorium; lower % yield |
| South Athens / Riviera avg | €3,200+ | Coastal premium |
| Glyfada | €3,500 to 5,500+ | Marina coast; Ellinikon halo |
| Voula | €4,000 to 6,000+ | Seafront premium; family demand |
| Vouliagmeni | €5,000 to 8,000+ | Ultra-premium; thin yield |
Note what the table implies for a fixed €800,000 on one deed: the cheaper the district, the more floor area the threshold demands, and the sooner it exceeds anything the local stock contains. Cheapness per square metre and reachability at this tier pull against each other.
Area guides: Glyfada property investment · Voula property investment
Yield, once the tier is applied
Read the yield table without a budget attached and the centre wins comfortably. Read the same table with €800,000 and a single-title requirement attached and the ranking inverts, because the rows that produce the high numbers are rows you cannot reach.
| Zone | Gross LTR yield (planning band) | Reachable on one €800,000 title? |
|---|---|---|
| Kipseli / transitional centre | 6 to 7.5% | No: the budget implies ~300 m² of stock that is not there |
| Athens city-wide average | 5.43% | Not a purchasable thing; a composite across all price points |
| Glyfada / Voula Riviera | 4 to 5.5% | Yes |
| Kolonaki / prime centre | 3.5 to 5% | Yes |
That leaves two reachable rows, and the coastal one is the higher of the pair. It is an uncomfortable result for the received wisdom about Athens, and it follows from a single structural fact: the yield districts are cheap per square metre, and a large fixed threshold on one deed converts cheapness into an impossible floor area.
Two honest caveats. The bands are planning ranges, not quotes on a specific flat, and a particular Kolonaki apartment with a strong corporate tenant can beat a mediocre Glyfada one. And the Kipseli case becomes real the moment the constraint relaxes: at the €400,000 regional tier outside Attica, or on a second non-qualifying purchase, or for a cash buyer with no residency objective at all.
Net yields after ENFIA, management, maintenance, and Greek rental income tax typically fall 1 to 1.5 points below gross. Model via Greece rental yield guide and buy-to-let Greece guide.
STR Moratorium: Center Constraint Riviera Avoids
Two separate restrictions stack in central Athens and only one reaches the Riviera. The national Golden Visa ban applies to any qualifying property anywhere in Greece, permanently, for the life of the permit. The Athens moratorium on new short-term rental registrations runs through the end of 2026 and applies to central districts regardless of Golden Visa status. So a central non-qualifying apartment may be unlicensable, while an equivalent Riviera one is not. Two STR rules stack in central Athens, only one applies on the Riviera for non-GV assets.
Layer 1: Golden Visa STR ban (national)
Law 5100/2024 prohibits short-term tourist rentals on the qualifying Golden Visa property everywhere in Greece. Applies to Kipseli and Glyfada equally.
Layer 2: Athens municipality moratorium (local)
The Athens STR moratorium freezes new ΑΜΑ licences in saturated central districts through end-2026. Zones include Kolonaki, Exarchia, Monastiraki, Koukaki, Petralona, and parts of the historic centre where STR density exceeded the 40% statutory threshold.
| Zone | New STR licence (non-GV) | GV asset STR |
|---|---|---|
| Center moratorium districts | Frozen through end-2026 | Prohibited always |
| Kipseli (typically) | Check current saturation map | Prohibited on GV asset |
| Glyfada / Voula | Standard ΑΜΑ rules | Prohibited on GV asset |
Practical impact: A yield investor buying center stock for LTR is unaffected by the moratorium, long-term leases remain fully legal. An investor hoping to STR a non-GV center apartment faces licence freeze; a Riviera buyer in Glyfada can still obtain new licences on non-GV stock, but cannot STR the GV qualifying unit anyway.
Full detail: Athens short-term rental moratorium 2026
Pre-moratorium licensed center properties trade at a premium, grandfathered ΑΜΑ numbers transfer with the property. That premium matters for non-GV investors, not for standard Golden Visa structuring.
Ellinikon Effect: Riviera Appreciation Driver
The Ellinikon, €8 billion regeneration of Athens’ former international airport, is the structural appreciation story for southern Attica. New parks, marina facilities, metro extension, branded residences, and hospitality anchors lift buyer attention across Glyfada, Voula, Vouliagmeni, Elliniko, and Alimos.
| Factor | Center | Riviera |
|---|---|---|
| Mega-project exposure | Indirect (metro links) | Direct Ellinikon halo |
| Coastal scarcity | No | Yes, limited seafront stock |
| International family demand | Moderate | High, schools, marinas |
| Price momentum (2025 ref.) | +6.1% apartments (Athens) | South premium widening |
Center appreciation rides urban gentrification, Metaxourgeio, Kipseli, areas along new metro lines. Riviera appreciation rides coastal regeneration and global second-home comparables (Nice, Barcelona coast).
Deep dive: Ellinikon Athens property investment
Liquidity and Resale Buyer Pools
| Factor | Center | Riviera |
|---|---|---|
| Domestic buyer depth | Very high | High (affluent suburbs) |
| Foreign buyer profile | Yield + GV + urban lifestyle | Lifestyle + family + EU second home |
| Transaction volume | Highest in Greece (5,816 Athens muni sales 2025) | Strong in Glyfada / Voula corridor |
| Resale seasonality | Year-round | Year-round; summer listing premium |
Athens municipality recorded 5,816 sales worth ~€626 million in 2025, liquidity is not a concern in either zone if pricing is realistic. Riviera resale often targets international families and EU coastal lifestyle buyers; center resale targets local professionals, students, and yield investors.
Compare national context: Greece property investment guide · best regions invest Greece property 2026
Pros and Cons
The two sides of this comparison do not fail in the same way. On the Riviera the risk sits in the entry price, where €800,000 buys steadily fewer square metres and the yield is thin by design. In the centre the entry price is the easy part and the risk moves to the street, the tenant and the moratorium. Each case is set out on its own terms below rather than scored against the other.
Athens Center (Kipseli / transitional)
| Pros | Cons |
|---|---|
| 6 to 7.5% gross LTR in Kipseli | STR moratorium in prime centre districts |
| Lowest €/m² in €800K zone for yield | Gentrification risk in transitional areas |
| Deepest year-round tenant pool | Noise, density, parking constraints |
| Metro connectivity | Lower lifestyle prestige than Riviera |
Athens Riviera (Glyfada / Voula)
| Pros | Cons |
|---|---|
| Ellinikon appreciation runway | Lower percentage LTR yields |
| Coastal lifestyle resale appeal | Higher €/m², less m² per €800K |
| Standard STR rules (non-GV assets) | Seafront premiums compress yield |
| International school / marina corridor | Competition from new Ellinikon supply |
Risks
Center risks
- Moratorium extension beyond 2026, policy direction toward tighter STR
- Gentrification volatility, pricing can lag or overshoot in transitional districts
- Building compliance on older apartment stock, engineer certificate critical
- Trophy centre purchases at low yield if chasing Kolonaki address
Riviera risks
- Ellinikon execution timeline, mega-projects can delay phases
- New supply from Ellinikon branded residences, competes with resale Glyfada stock
- Coastal premium compression if yields normalise nationally
- €800,000 concentration, fewer buyers at exit above €1.5M trophy Riviera
Shared Attica risks
- GV STR ban on qualifying asset
- 7 to 10% acquisition costs, cost of buying property Greece
- Foreign inflows −25.3%, selective buying required
- Due diligence on 78% resale-dominated foreign market, due diligence Greece property
Buyer scenarios
The two locations suit opposite objectives at the same €800,000 threshold. A yield-focused buyer should take Kypseli or the transitional centre and target 6.0% to 7.5% gross, accepting the moratorium context because long letting is unaffected by it. A residency-and-lifestyle buyer should take Glyfada or Voula, accept 3.8% to 4.5%, and underwrite the exit to an international buyer rather than the rent.
Scenario A: Yield maximisation at €800,000
Choice: Kipseli or transitional center districts. Target 6 to 7.5% gross. Accept moratorium context, LTR is unaffected.
Scenario B: Family lifestyle + Golden Visa
Profile: EU family wanting coastal schools, marinas, weekend beach access.
Choice: Glyfada or Voula. Accept 4 to 5.5% gross LTR. Ellinikon as appreciation hedge.
Scenario C: Appreciation-led hold
Profile: Long hold (10+ years), personal use summers, resale to international buyer.
Choice: Riviera, Glyfada seafront or Voula hillside with Ellinikon proximity.
Scenario D: Portfolio within Attica
Profile: €1.6M+ total, split qualifying GV unit and income satellite.
Structure: €800K Kipseli LTR (yield) + personal Riviera use property (non-GV or second structure, legal counsel required). Or €800K Riviera GV base + smaller center apartment for LTR on non-qualifying title.
Scenario E: Compared to €400,000 regional Greece
Profile: Investor questioning whether €800,000 Attica beats €400,000 Crete.
Read: Crete vs Cyclades property investment and best regions invest Greece property 2026.
Decision Matrix
| Your priority | Lean toward |
|---|---|
| Highest gross LTR yield | Center, Kipseli |
| Ellinikon appreciation | Riviera, Glyfada / Voula |
| Coastal lifestyle resale | Riviera |
| Metro urban tenants | Center |
| New STR on non-GV asset | Riviera (not center moratorium zones) |
| Lowest €/m² in €800K zone | Center transitional districts |
| International family buyer pool | Riviera |
Verdict
For a Golden Visa buyer at €800,000 on a single title, the Riviera is the stronger choice on income and on lifestyle at once, which is not the trade-off this comparison is usually said to present. Glyfada and Voula stock reaches the threshold at a realistic floor area, yields 4 to 5.5% gross against Kolonaki’s 3.5 to 5%, and carries the Ellinikon appreciation case on top.
The centre earns the decision on different grounds: a buyer who wants to live in Athens rather than beside it, who values a year-round tenant pool over a seasonal one, or who is buying prestige stock whose resale market is domestic and deep. Those are good reasons. Higher yield, at this threshold, is not among them.
Both zones share the €800,000 threshold, the 120 m² rule, and the GV STR ban. The moratorium adds a center-only constraint on new STR licences through end-2026, relevant for non-GV plays, not for standard GV LTR underwriting. Start with the Athens property investment guide for the full submarket map, then drill into Glyfada or center yield districts with your lawyer and engineer before deposit.
Financial Comparison of Athens Riviera vs Athens Center
Run at net rather than gross, both options land well under the yields quoted for cheaper Athens stock, and for the same reason: Greek rental income is taxed progressively at 15%, 25%, 35% and 45% on gross rent, with only a flat 5% repairs deduction to set against it, so an €800,000 asset pays the upper rates on most of its income. Modern Riviera stock with parking and a good energy rating nets around 2.4%. A renovated 1970s Kolonaki flat nets closer to 1.7%, because prime capital value does not translate into proportionally higher rent and the maintenance reserve on older stock is real.
| Financial Metric | Option A: Athens Center (Kolonaki) | Option B: Athens Riviera (Glyfada) |
|---|---|---|
| Purchase price | €800,000 | €800,000 |
| Floor area | 110 m² | 135 m² |
| Price per m² | ~€5,409 Kolonaki | ~€4,250 to €5,000 Glyfada |
| Stock | 1970s block, renovated | 2021 build, parking and balconies |
| Monthly long-term rent | €2,900 | €3,500 |
| Gross annual rent | €34,800 | €42,000 |
| Gross yield | 4.35% | 5.25% |
| Greek rental income tax (15/25/35/45%, after the 5% repairs deduction) | €7,971 | €10,855 |
| Management (8%) | €2,780 | €3,360 |
| Vacancy allowance | €1,740 (5%) | €2,520 (6%) |
| Maintenance reserve | €4,000 (0.5%, older stock) | €1,600 (0.2%, new build) |
| ENFIA | €2,300 | €2,100 |
| Buildings insurance | €1,400 | €1,500 |
| Accountancy and non-resident filing | €900 | €900 |
| Net annual income | €13,709 | €19,165 |
| Net yield on purchase price | 1.71% | 2.40% |
| 120 m² Golden Visa rule on a single title | Fails at 110 m² | Passes at 135 m² |
Option B (Athens Riviera) delivers roughly 40% more net income than Option A on identical capital, driven by higher rent per euro invested, a much lower maintenance reserve on new-build stock, and demand from tenants who will pay for parking and energy performance. It also clears the 120 m² Golden Visa minimum on a single title with room to spare.
Option A (Athens Center) commands a premium location in Kolonaki but carries higher maintenance costs due to the building’s age, and the 110m² size fails the 120m² Golden Visa requirement unless the buyer is exempt or utilizes a non-residential conversion route. Center properties, however, benefit from year-round domestic and corporate demand, making them highly defensive assets during economic downturns.
Sub-Market Selection Checklist for Buyers
- Tenant Profile and Lease Terms: Center properties attract diplomats, corporate executives, and academics who prefer 1-2 year leases. Riviera properties attract affluent families and expats who demand multi-year leases and premium amenities (parking, security, pools).
- Golden Visa Compliance: Both locations sit in the €800,000 Attica zone. However, finding modern apartments over 120m² is significantly easier on the Riviera, whereas Center apartments are often smaller and require legal mergers of adjacent units to qualify.
- Capital Appreciation Potential: The Athens Riviera is undergoing massive transformation driven by the Ellinikon project, leading to higher projected capital growth. The Center offers stable, mature values with lower volatility but compressed yields.
Frequently Asked Questions
For a Golden Visa buyer at the €800,000 threshold, the Riviera. Kipseli's 6 to 7.5% gross is real but unreachable on one deed at that budget, because €800,000 at €2,400 per square metre implies roughly 300 square metres and that stock does not exist in transitional Athens. The centre you can actually buy at €800,000 is Kolonaki grade, yielding 3.5 to 5% against Glyfada and Voula at 4 to 5.5%. Buy the centre for the city itself and its year-round tenant pool, not for yield.
Yes. Law 5100/2024 classifies the entire Attica regional unit as a prime zone. Glyfada, Voula, Kipseli, Kolonaki, and all Athens municipality districts require €800,000 minimum in a single residential property of at least 120 square metres usable area. Short-term tourist rentals are prohibited on the qualifying asset nationwide.
City-wide the centre averages €3,400+ per square metre at 5.43% gross, and Kipseli reaches 6 to 7.5% on long lets, while South Athens and the Riviera average €3,200+ at 4 to 5.5%. Those city-wide figures mix every price point, so they answer a different question from the one a Golden Visa buyer is asking. Restricted to stock a single €800,000 title can actually buy, the comparison is Kolonaki at 3.5 to 5% against Glyfada and Voula at 4 to 5.5%.
The moratorium freezes new ΑΜΑ short-term rental licences in saturated central districts, Kolonaki, Koukaki, Exarchia, Monastiraki, through end-2026. Glyfada, Voula, Kifisia, and Marousi operate under standard STR licensing rules for non-GV assets. Golden Visa qualifying properties cannot STR regardless of zone. Center buyers face a double constraint: moratorium plus GV ban.
Glyfada and Voula coastal stock often runs €3,500 to 5,500 per square metre on quality resale; Vouliagmeni premium exceeds that band. Kipseli and transitional centre districts sit €2,000 to 2,800 per square metre, lower entry per square metre within the same €800,000 tier, which drives higher percentage yields on LTR.
The Ellinikon is an €8 billion regeneration on Athens' former airport site in southern Attica. It lifts infrastructure, marina capacity, and international buyer attention across Glyfada, Voula, Vouliagmeni, Elliniko, and Alimos. Center districts benefit indirectly through metro connectivity but lack a single project of comparable scale, their thesis is yield and urban gentrification rather than coastal mega-development.
Buy Riviera if you want coastal lifestyle, Ellinikon appreciation exposure, family-suburb owner-occupier resale, and can accept 4 to 5.5% gross LTR. Buy center, Kipseli, Mets, transitional districts; if yield optimisation at 6 to 7.5% gross LTR matters more than sea views. Both suit Golden Visa buyers at €800,000 who will hold long-term.
No on the qualifying Golden Visa asset in either zone under Law 5100/2024. Separately, new STR licences are frozen in moratorium central districts through end-2026 even for non-GV owners. Riviera suburbs such as Glyfada allow new ΑΜΑ licences under standard rules, but that does not override the GV STR prohibition on the residency-qualifying unit.
Next steps: the Golden Visa hub.
Read next
Property for Sale in Athens: Prices by District, 2026
Kolonaki asks about €5,409 per m² and Patisia €1,731, a threefold spread inside one city. Where the Riviera sits, and why Athens yields beat the islands.
Athens Airbnb Moratorium 2026: Zones, Rules and Impact
Athens STR moratorium through end-2026: density caps in Kolonaki, Koukaki and centre. Separate from the Golden Visa rental ban, rules explained.
Athens Golden Visa €800K: Which Areas Qualify in 2026
Athens €800K Golden Visa zone: Piraeus, Glyfada, Voula, Vouliagmeni, Ellinikon. Prices, 120m² rule and area guide for 2026.
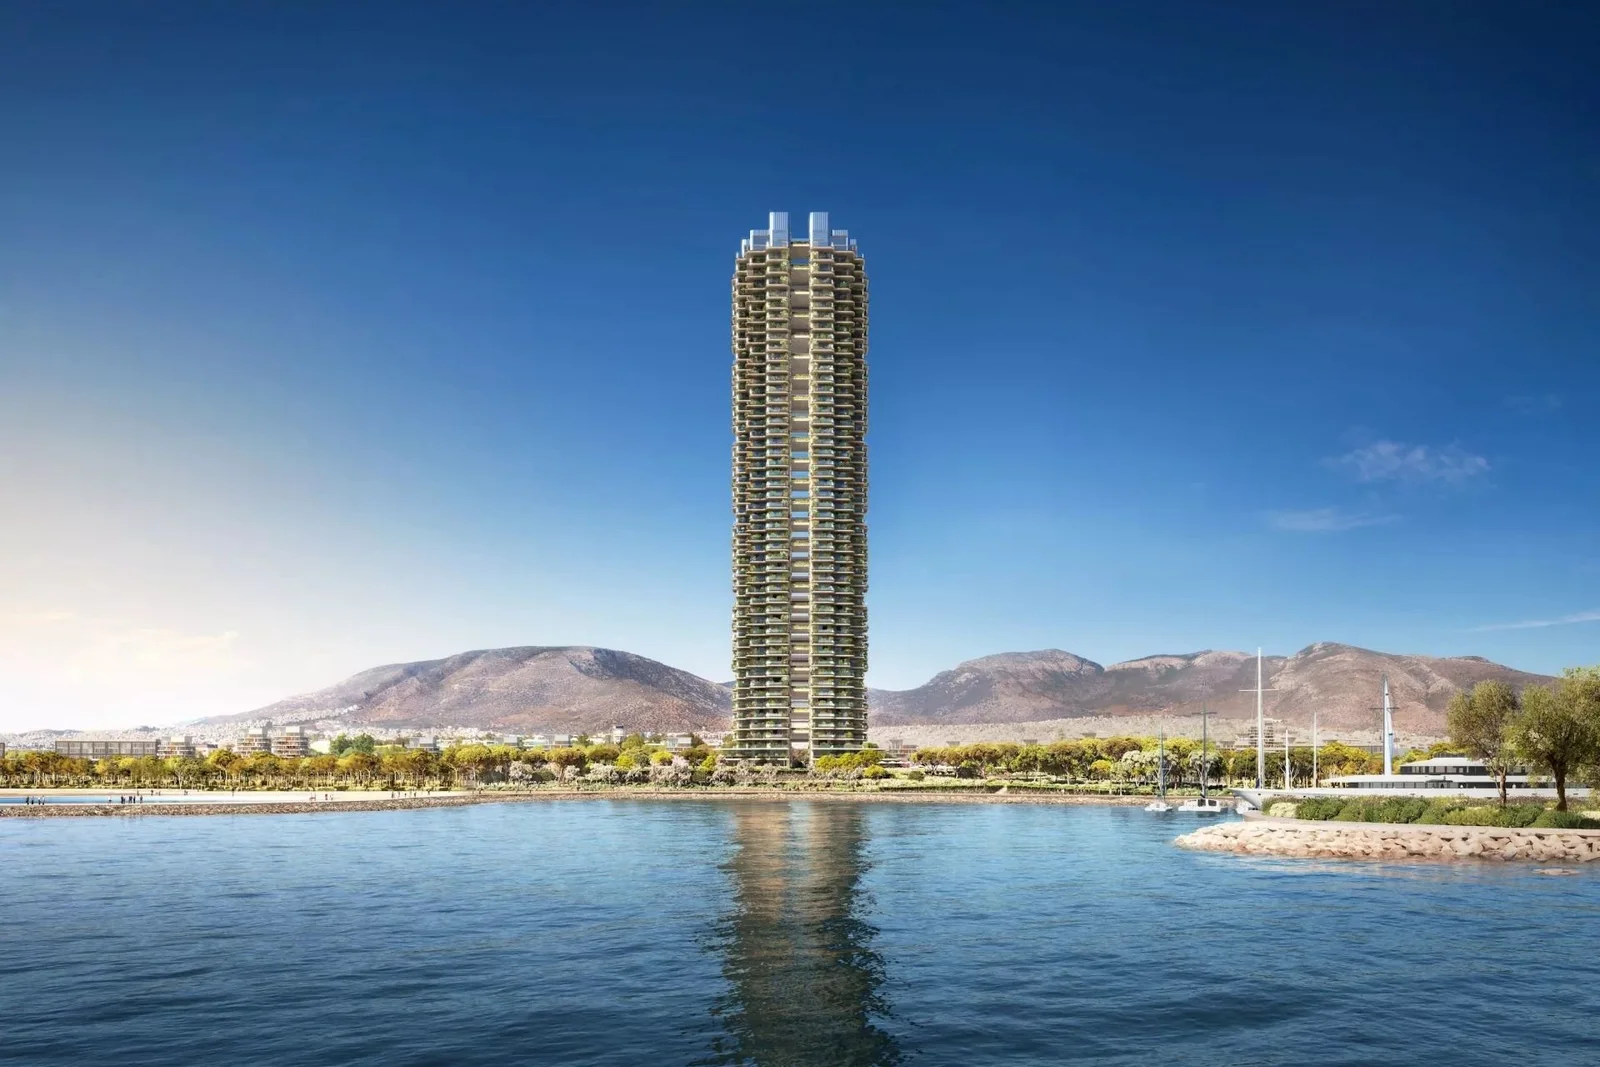
The Ellinikon: Athens Riviera Property Investment 2026
Ellinikon Athens: Lamda's €8B regeneration on 6.2M m², €3,200+/m² Riviera pricing, Golden Visa fit, zones, timeline, risks and buyer profiles.
Best Regions to Invest in Greece Property 2026 Guide
Ranked 2026 guide: Attica, Crete, Cyclades, Peloponnese, Thessaloniki, Halkidiki, Golden Visa tiers, yields, entry prices, and buyer fit.
Greece Golden Visa Property Tiers 2026: €800K vs €400K
Law 5100/2024 created three Greece Golden Visa tiers. Compare €800K prime zones, €400K regional, and €250K conversion thresholds to pick the right investment.
Get your Greece property shortlist
Share your budget, region (Athens, Crete, islands, or Peloponnese), and Golden Visa goal. We reply within one business day with matched options and next steps.